Many people in the United States think it would be great to give the rest of the world Democracy. Right now, millions of Egyptian Muslims are rioting, who by just voting and winning one election, think that the army has ripped Democracy away from them. If you are uneducated poor and starving, you cannot afford Democracy, it has no meaning. It’s a little like a terminally ill person winning the lottery, the money means little. Democracy has nothing to do with winning an election and then telling everyone around you how to reproduce, live and worship. Hmm— on second thought I could be wrong on that---
Obamacare for everyone including those with extreme health issues and no insurance sounds very noble. There is one problem, Health insurers have figured out that really sick people don’t work, so if they drop individual policies, they eliminate those people who could be their greatest liability. And of course, if the health care insurers raises rates too high, they will be banned from selling insurance—kind of reminds me of the quote “Please Brier Bear, don’t throw me in the Brier patch.” Employers have figured out that keeping the number of employees under 50 does have advantages. And of course keeping the work week short, under 30 hours, keeps benefits low. How all this will help a hamburger flipper get health care coverage escapes me.
Feeding the worlds starving masses seems very noble also. The trouble is if the world population increases another two billion---then, people have to starve and die, in order for your family to have the food they need to survive. Our world is a little like a fruit fly experiment, where you enclose one banana and two fruit flies in a beaker and watch what happens. You end up with a beaker of fruit flies and no banana (assuming the flies are not gay).
Many think the burning of fossil fuels is having no environmental impact on our world. But the catastrophic weather of the last year or two has been very unsettling. Let’s hope it’s part of a cycle that is over for now. We can ban the burning of coal, but we can’t stop the mine owner from selling his coal to China. Also, the idea that the government subsidization of the production of ethanol is going to solve the oil shortage, doesn’t really work. A gallon of gas with 15% ethanol doesn’t produce the gas mileage of the real thing. It does however raise the price of beef (corn fed cattle may be a thing of the past). Converting food to ethanol, to burn in an auto and paying people extra to produce it, is only something that the "Sad Sack" group in Congress could think up.
The thing not realized with all of the above mentioned, is that we have created ways of life that revolve around models that have worked well for us in the past, like the phrase; “Real estate will always go up in value. “ What most people haven’t realized, is that the game is changing, but our thinking hasn’t. It’s often repeated; ”The USA is the greatest country in the world.” It was at one time. Repeating the phrase doesn’t validate it; but repetition is a form of personal validation, and it works quite well. We don’t consider ourselves as fruit flies, but what the rest of the world does, could finish off the banana. Everything is inter-related. The new phrase to repeat is; “Technology will save us.” Start repeating it! If you don't like that phrase, try this one; "I am not a fruit fly." Repetition will be our salvation ;>). Enjoy the banana.
Saturday, July 13, 2013


Saturday, June 29, 2013
Who Pays Taxes, Is The Real Game
Buy a house, for 600k in California pay a property tax of $6,000 a year. Buy a car for 40K. Pay $4,000 in sales tax. Buy $10,000 of taxable goods add on another $1,000. Income tax on 100K add on about $18,000. Social Security and Medicare, add about another $10,000. Then there is a gasoline tax, telephone tax, electricity tax. The tax people pretty much know where you live.
So for a 100k salary, with husband and wife working, looking at the chart below, after taxes, you’ve got 71K. Subtract the other items on the list and what’s left over---about $6,000.

Surprisingly the third group living at the poverty level on my spread sheet seems to have the ability to get by almost as well as the middle group earning 50K. Food stamps are a big item, as well as one adult being able to stay home to manage the children without having to pay for day care. With the medical benefits, there is almost an assumed incentive for larger families.
What can we learn from all of this? First off, I should probably be shot for the quite arbitrary excel spread sheet. I kind of modeled the spread sheet to my family even though we don’t have expenses for student loans, car payments or day care. Of course having a son going to Berkeley is kind of a wash. The thing that impressed me was the realization, that 100K of income in California is not upper middle class. Let's face it, what do I have left to put in the bank for retirement? Our family's current earnings feel good only because we can remember making a lot less in the past.
When I was an engineering student, many a time we took a napkin and with some rudimentary drawings, we arrived at answers that pointed to problems that were not apparent. It’s obvious to me that in order to save more for retirement, there isn’t much left that our family can cut. It also appears, that many people in this country will when given time figure that health care and car insurance are not a necessary thing. This is probably where Obamacare will crash and burn on the economic highway. It is obvious that Congress needs to raise taxes, and I cannot afford to pay more, to support those now paying less. How do we as a nation determine what is each person’s fair share of taxes? Let's tax those that pay no taxes now and cut off benefits to those that have not paid taxes. The damn thing is that won't float, no Democrat would ever get reelected. Go Figure! I'm really getting tired of the free lunch program. This country was founded on "Pay as you go," not,--- "Uncle Sam will pay, if you're too poor."
So for a 100k salary, with husband and wife working, looking at the chart below, after taxes, you’ve got 71K. Subtract the other items on the list and what’s left over---about $6,000.

Figure the same scenario for a family of 4 with one wage earner making 50K. No new car, figure same amount on taxable goods of 1,000, zero income tax. Rent payment figure $20,000, no health or student loan. Take off 3k for utilities, forget car insurance and figure 4 k for gas and car repairs. The same 6k as rich people for food. No day care, the wife doesn’t work. Spending money after expenses is about 10K. The $10,000 is almost illusionary for this group, going to the dentist or one car accident is all it takes.
Surprisingly the third group living at the poverty level on my spread sheet seems to have the ability to get by almost as well as the middle group earning 50K. Food stamps are a big item, as well as one adult being able to stay home to manage the children without having to pay for day care. With the medical benefits, there is almost an assumed incentive for larger families.
What can we learn from all of this? First off, I should probably be shot for the quite arbitrary excel spread sheet. I kind of modeled the spread sheet to my family even though we don’t have expenses for student loans, car payments or day care. Of course having a son going to Berkeley is kind of a wash. The thing that impressed me was the realization, that 100K of income in California is not upper middle class. Let's face it, what do I have left to put in the bank for retirement? Our family's current earnings feel good only because we can remember making a lot less in the past.
When I was an engineering student, many a time we took a napkin and with some rudimentary drawings, we arrived at answers that pointed to problems that were not apparent. It’s obvious to me that in order to save more for retirement, there isn’t much left that our family can cut. It also appears, that many people in this country will when given time figure that health care and car insurance are not a necessary thing. This is probably where Obamacare will crash and burn on the economic highway. It is obvious that Congress needs to raise taxes, and I cannot afford to pay more, to support those now paying less. How do we as a nation determine what is each person’s fair share of taxes? Let's tax those that pay no taxes now and cut off benefits to those that have not paid taxes. The damn thing is that won't float, no Democrat would ever get reelected. Go Figure! I'm really getting tired of the free lunch program. This country was founded on "Pay as you go," not,--- "Uncle Sam will pay, if you're too poor."
Saturday, June 22, 2013
Commodity Prices Are Dropping
Gold, Platinum and Silver have taken quite a hit in the last few weeks. To a lot of people these metals are investment and as such, they follow the prices quite intensely. I know my wife has been tracking their prices for quite a while. So she sees a loss in our portfolio from their highs to their present lows and points out to me that we could have purchased a BMW with our losses.
There is a reason for buying gold and silver and it has nothing to do with investments. If Bernanke starts this tapering off of purchasing T-bills and real estate paper, interest rates have to rise. If they rise to 8.5 percent, the total amount collected in taxes in the United States will only pay the interest on the National Debt and at that point, the country is bankrupt.. I was discussing this conundrum with my wife; she said “well they will just print more dollars to pay it off.”
The thing to realize here is that gold, silver and platinum have value not determined by any government. Their net worth at any point in time tends to be relative to wages in general. As a measure of worth, assume that an ounce of silver is one day’s wages, an ounce of gold is one week’s wages and an ounce of platinum is probably worth a lot more. Don’t hold me to the values stated; they are just a guide for survival. What you are looking at here is a way to preserve part of your wealth in a tangible way. 1,000 ounces of silver is going to provide you about three years of income if the dollar was to tank. One ounce of gold would pay the rent for a month. What we are really purchasing is peace of mind and security for the future.
To a lot of people, if gold went to $10,000 an ounce, they would sell, but think about it. Has gold or silver really appreciated over time? In 50 years silver has risen from a dollar an ounce to about $20 an ounce. Real estate prices have risen in the same time span from $28,000 to $280,000. A pack of cigarettes has risen from 21 cents a pack to six dollars. Do you sell gold at $10,000 only to find out that a loaf of bread and a package of hot dogs is $5,000? If you think gold could drop to 30 dollars an ounce, do you think that cigarettes could drop back to a quarter a pack?
So when you see the price of silver and gold drop, relax it is of little concern. Realize one thing, the reason you are holding them is because of government foolishness. Inflation is their mistress. Profit is not your motive; preservation of a portion of your wealth is the objective.
Just as food for thought, in 1964, when I was being paid $2.00 per hour, I could buy 16 ounces of silver for a day worked. So take 16 oz. of silver time $22 spot today and you get $352. Divide that by 8 hours and you get $44 dollars an hour. I guess that explains why my mom didn’t have to work when I was a kid. People made real money back then. Our standard of living has dropped considerably, both the husband and wife work today. But by God, we are making 10 times the $5,000 my dad brought home a year—and paying 10 times more in taxes. Anybody catching on to what is happening???? Our employer gives us a pay raise because the government printed more dollars? We get happy. Are we getting richer? The raise feels good, it just doesn’t go very far.
Monday, June 17, 2013
The Deflation Factor
Many people believe that the US could be facing deflation similar to what happened in the 1930’s. And of course Ben always claims he’s running the printing presses to keep that from happening.
Here is what happened during the Great Depression. The stock market crashed in 1929 and it wasn’t uncommon for someone on margin to lose 4 times their investment. Then in the 1930’s the banks collapsed. When it was all over, the average person with $10,000 in savings ended up with about $1,000, a loss of 90 percent of their accumulated wealth. There were no food stamps, welfare, social security, company retirement plans, credit cards or unemployment insurance. If you owned a home with a mortgage, you had a problem. Most home loans were for 5 years, and very few were being renewed the banks; they needed the cash. You either paid off the loan or lost the house to the bank.
Consumption fell off a cliff in the 1930’s.If you had no money you were not in a position to stimulate the economy. If you were a business, sales were down to say the least. Most business of the time did not reduce wages, so in effect with the deflation your paycheck bought more (if you were employed).
Let’s fast forward to today. We had a real estate crash and no one lost a dime. We had a bank collapse and all deposits were insured. The unemployed have two years of unemployment. Food stamps for all that apply. The stock and bond markets have rallied. The government is spending 150% of what it takes in in taxes each year. And of course, the national debt has increased to 17 trillion dollars. Washington is going to save us by spending what we don’t have to spend.
If people want to argue over whether or not this is a global depression, be my guest. The real question is how long can government spending programs continue in this largess manner? No wonder, consumption has not fallen off of a cliff. It’s irritating to say the least, that entitlement programs allow the user more freedom to manage their discretionary income (A cell phone and cable TV are essential necessities). Being unemployed does not make you homeless and broke. This time around, you can move in with mom and dad; most kids’ parents live longer now.
Things are different this time. No money was lost, and failure was rewarded by bailouts and insurance. Low interest rates have literally ruined many retirement plans made 30 years ago with the assumption interest rates on savings would offer a return greater than inflation.
The deflation of the 1930’s was caused by too little money chasing too many goods. In today’s world, we have too much money chasing too few goods. Plus there is the interest rate factor. Why not spend your earnings on immediate gratification? The future reward (interest) for deferred consumption just isn’t there.
In today’s world, wages remain unchanged and purchasing power has decreased noticeably. World governments owe debts that cannot realistically ever be paid back. Just the thought of paying part of the debt off, creates riots in the streets; entitlements are where the cuts are made. The world in a global sense doesn’t appear to be clutches of deflation. People now have to work harder and longer to keep up with what they had the year before. Our standard of living is decreasing at a slow but noticeable rate. Next year many people in the US will earn the same amount but have $5,000 to $10,000 less to spend with the new health insurance.
Technically the health care tax should plunge us into a deflationary spiral. But the thing that will be most noticeable will be the future decrease in Federal tax revenues collected. Bernanke will be just like the high school kid that smokes a couple of packs of cigarettes and thinks he can quit at any time. The printing will have to continue.
The troubling thing I find right now is in the financial and real estate markets, people are so receptive to all of the experts. There is an answer and an explanation for every event. 40 years ago there was a complete disconnect between the experts and the markets -- That was the reason you had a stock broker, no layman could figure it out--IBM announced terrific profits and the stock dropped 15 points--go figure! In reality if the experts were any good at what they did, they wouldn’t have to work for a living; of course nobody’s going to point that out on a business program.
So what’s it going to be, deflation or hyperinflation? Deflation would make the national debt a lot harder to pay off; of course that’s already an impossibility, even at these very low interest rates. Congress is on a roll, spend whatever you have and don’t have.
What we need to realize here, is that we have a government machine borrowing our savings and spending it at a very fast and furious rate. Will we get it back when we go to retire? Do you expect the government to say "NO?" Ben's going to save us from deflation, well Go(l)d bless him.
Sunday, June 02, 2013
The Economy Is Improving?
I can’t quite figure it out. It looks like they added more punch to the punch bowl. The party is on again. Housing prices are up 10% and stocks are climbing ever higher. It’s kind of hard to figure out what investor would loan money to home buyers at 3.5 percent interest for 30 years; maybe for one or two years, but not 30. You can get a better return on you dollars in the stock market.
So let’s see how the game works. Ben buys all treasuries and real estate loans presented for sale. This keeps interest rates low. Since the banks are paying very little interest, retirees withdraw their retirement funds and “invest” it in the stock market. This makes stock prices rise and that increases the fervor to put more money in the market. Of course the low interest rate loans stimulate buying stocks on margin and increases commodity speculation. Borrowing a million or two to speculate in the oil market would only cost 30 to 60k per year. Plus it’s a business expense.
Silver and gold are still dropping. The coin dealer I buy silver Maple leafs from, is out again. He can’t seem to order it fast enough. If we’re coming out of a recession, why is a bullion dealer running out of product? It reminds me of a movie theater; if you smell smoke, don’t yell “FIRE” until you get to the exit.
Then we have the health care plan kicking in. The young, if they want coverage, will be $130 a month at a minimum. See the two charts below for pricing in Kalifornia.


The penalty for not buying insurance will be $95 next year and go up to $695 per person in 2016-- to a max of $2085 for a family of three or more. Of course if you earn less than $9,500 a year, there is no fine. I’m not quite sure how this affects the future price of produce harvested in California. But if you do the math, for a family of 4, if the wife can’t make more than $10 per hour, she’s better off economically and financially, sitting home and taking care of the kids, while the husband works. Daycare is not cheap. Notice if you earn less, you qualify for more benefits; whereas if you earn more, you qualify for a heavier dose of taxation.
California announced that they went from a 25 billion dollar deficit to an 851 million surplus in a little more than 2 years. You do have to wonder what they “threw under the bus.” It sounds like someone from Disneyland is doing the state’s accounting. Of course there is not a peep about the state’s unfunded pension liabilities that have topped half a trillion dollars – six times the present state budget (study by Stanford Institute for Economic Research).
The housing bubble is gone. Real estate is being bought as an investment that can return 3 to 6 percent over what the banks pay. What created this was a Federal Reserve policy. They have been buying the real estate paper and the redeemed treasuries – thus keeping interest rates low. It’s a little like squeezing a balloon, it pooches out in another direction. Seniors and investors now see the stock market as the “last bastion of investment” (fancy words for a bubble).
There are two private sector bubbles; the bond market, the stock market, and then there is the national debt. The real question is, which shoe drops first-- -the bond market or the stock market? It’s a 50/50 call. You are going to buy puts either way. It will be a one two punch, one bubble will pop and then the other a little while later. And of course, there is the national debt, whose size nobody can even comprehend.
The one economic condition that could collapse this house of cards is Obama’s health care. What would have gone for vehicle insurance in many family budgets, will now go for health insurance. One of the things that made America great was the ability of each family to choose what they spent their earning on. Naturally they neglected saving for retirement and health care in order to give their kids a chance at a better life. Money used wisely is a tool you use to craft your life like a carpenter building a house. Each person individually tries to determine their own destiny. So follow the chain: no car insurance---you wreck your car or have it stolen--you lose your job because you can't get to it-- money problems lead to a divorce and drugs,---downhill from there. The poor are being set up for failure. It reminds me of the story about the battle that was lost over a missing nail in a horseshoe.
The real question is this, how do higher taxes and more government regulations induce increased economic prosperity? Common sense suggests that the people with all of the answers, are part of the problem. Economic issues are never solved by government, only shifted into another direction. Every student in the US is entitled to a college education with government financing. If enough people graduate, you might just need a degree to get a job flipping hamburgers. But I digress; the economy is just doing great. It's the people around me that aren't.
The real question is this, how do higher taxes and more government regulations induce increased economic prosperity? Common sense suggests that the people with all of the answers, are part of the problem. Economic issues are never solved by government, only shifted into another direction. Every student in the US is entitled to a college education with government financing. If enough people graduate, you might just need a degree to get a job flipping hamburgers. But I digress; the economy is just doing great. It's the people around me that aren't.
Wednesday, May 22, 2013
The Inequity of Democracy
Last Friday the Wall Street Journal had an article on their opinion page “The Economics of a $6.75 Shirt.” The writer Rubana Huq is the managing director of the Mohammadi Group, a garment manufacturer and exporter in Bangladesh. His discussion touched on the current wage over there for garment workers of $70 to $80 dollars a month working two hours of overtime a day. He claimed that the labor cost per shirt was about 38 cents and the cost of materials was about $5.75. I tend to think that his cost of materials could be one or two dollars lower, but it reads good.
He went on to describe how the garment worker paid $40 dollars a month for rent and $13 per month per adult for 30 kilograms of rice. It kind of reminds me of when I was in Viet Nam in 1968. The wage scales and rents over there were about the same. I’ve heard a Congressman or two suggest that we need to bring back the clothing manufacturing back to the USA. The only thought that comes to mind is what were they smoking? Fast forward to today, many thousands of people emigrated from Viet Nam to the US. These people have been a real success story. They came from a world deep in poverty.
Over three quarters of the world’s population is working for slave wages, while we in this country are oblivious to the fact. Democracy is a system that allows us to inadvertently take advantage of other less developed countries. When you ask a supplier what is his bottom line on cost for producing a shirt or a cell phone is, his employees don’t even enter the equation. Low prices drive our cell phone and wide screen TV consumption.
What we are looking at is two worlds; those with real income and those living from hand to mouth. The one thing not understood by Americans is the slavery aspect of the third world. Work until you die or starve to death. In this case, having more kids is a retirement plan. The concept works but for all the wrong reasons-- an increase in the population decreases the food available for everyone.
This is where Islam is gaining support. The United States is the “Great Satin” because we benefit greatly from the sweat and toil of people in third world countries and they get little in return. Our government is claiming the recession is over, but if people in the US are consuming less, it affects these third world countries drastically. These are the countries facing substantial wage deflation pressures and possible starvation. People with a job, have no time to protest at these slave labor rates, but if unemployed, why not turn out for a riot and vent some anger?
The world seems to be in turmoil, and everything appears normal in the United States (if you’re a Democrat). The trouble is, a lot of seemingly unrelated items weave together to make us appear to be the cause for poverty in the third world. A cell phone made stateside might range in price from $500 to $1500 and an Ivy League button down shirt might cost upwards of $50. If we produced these items over here, we couldn’t go out to dinner as often as we liked plus the people that were previously building them would be unemployed and most likely starve to death.
Obama wants to give the third world Democracy. It’s kind of like passing out shoes to people with no feet. What they really need is some sort of support system for wages and food. Religious organizations seem to be the best avenue of support, whether they be Islam or Christian. The thing we need to comprehend is the inner rage of these souls in third world countries that can turn on a TV and view the world that they can only see, but not touch.
I propose a solution. Invade Mexico and make it the 51st State. As a state the minimum wage would increase and the people here illegally would now be citizens. And their country under American law would make it a very nice place to want to live. The neat thing about that, we wouldn’t have to wait for Congress to attempt to pass an immigration bill. And from there, statehood for South America.
It sounds ludicrous, but maybe Egypt or Libya might want to become the 51st state. There are definite advantages of statehood, the only problem, I doubt if any of these foreign countries have anyone in their ranks stupid enough to be a Congressman.
Sunday, May 05, 2013
Let’s Do the Math
Here’s a quote from Bloomberg.com September 13,2012:
The biggest problem for a bank, is loaning money long term at low interest rates. Depositors don’t put their saving in a bank for 30 years; they move it around to get a better rate. Banks have no desire to finance 30 year home loans at these rates, when they can service your Visa card loan at 18 percent. They'll write the loans and sell them to the secondary market, and guess who's buying them? The Federal Reserve, in theory, can finance the loans and wait out the full 30 years for repayment and not lose a dime on the deal.
There comes a point where the Federal Reserve has to choose between becoming the financial institution of choice for our real estate market, or get out of it. If and when they exit, interest rates should jump a couple of percent. The neat thing at this transition, a larger portion of the people holding real estate will have “skin in the game.” Most of the liar loans will be off of the books.
What will happen to the real estate market when the Federal Reserve stops buying home loans? Who will step in to provide financing? This implies a future rise in interest rates. A significant rate increase could trash the bond market. And of course the interest paid by us on the national debt would go up accordingly.
Ben’s not traveling to Jackson Hole this year for the meeting of the world’s financial wizards; he has a “previous engagement” which I find hard to believe. Tim Geithner already left at Treasury (very silently) and his replacement has noticeably kept his mouth shut. Bernanke not showing up at Jackson Hole, and Tim leaving, kind of suggests a reshuffling of policy for the world bank which they were the head of, and controlled. Several countries are repatriating their gold from our shores. Nobody has yelled "fire" yet, but this looks like an obvious move towards the exits.
How do we interpret the actions of Tim Geithner and Ben Bernanke? Is there a policy change underfoot that key people disagree with? The only thing that bothers me is the annual 3.3 million home loans the Federal Reserve bought to save our real estate market from ruin. And if you read the papers, real estate sales are picking up --gee, I wonder why? --and for how long?
The Federal Reserve said it will expand its holdings of long-term securities with open-ended purchases of $40 billion of mortgage debt a month in a third round of quantitative easing as it seeks to boost growth and reduce unemployment.The Federal Reserve is buying 40 billion of real estate loans per month. The median price of a home in the US for December of 2012 was $180,000. Figure the banks want a 20 percent down payment. That comes out to 36K with a loan amount due of 144k. Take the 40 billion dollars and divide that by $144,000. That figures out to 277,778 home mortgages purchased per month. Just to kick this dead horse one more time multiply that amount by 12 months. The grand total is 3.3 million homes. The total number of homes sold in 2012 was 4.96 million. It kind of looks like the Federal Reserve holds a hell of a lot of home loans; almost 3/4ths of everything written last year. Of course, I must admit that I thought there was something seriously wrong with my pocket calculator when I first ran the numbers.
The biggest problem for a bank, is loaning money long term at low interest rates. Depositors don’t put their saving in a bank for 30 years; they move it around to get a better rate. Banks have no desire to finance 30 year home loans at these rates, when they can service your Visa card loan at 18 percent. They'll write the loans and sell them to the secondary market, and guess who's buying them? The Federal Reserve, in theory, can finance the loans and wait out the full 30 years for repayment and not lose a dime on the deal.
There comes a point where the Federal Reserve has to choose between becoming the financial institution of choice for our real estate market, or get out of it. If and when they exit, interest rates should jump a couple of percent. The neat thing at this transition, a larger portion of the people holding real estate will have “skin in the game.” Most of the liar loans will be off of the books.
What will happen to the real estate market when the Federal Reserve stops buying home loans? Who will step in to provide financing? This implies a future rise in interest rates. A significant rate increase could trash the bond market. And of course the interest paid by us on the national debt would go up accordingly.
Ben’s not traveling to Jackson Hole this year for the meeting of the world’s financial wizards; he has a “previous engagement” which I find hard to believe. Tim Geithner already left at Treasury (very silently) and his replacement has noticeably kept his mouth shut. Bernanke not showing up at Jackson Hole, and Tim leaving, kind of suggests a reshuffling of policy for the world bank which they were the head of, and controlled. Several countries are repatriating their gold from our shores. Nobody has yelled "fire" yet, but this looks like an obvious move towards the exits.
How do we interpret the actions of Tim Geithner and Ben Bernanke? Is there a policy change underfoot that key people disagree with? The only thing that bothers me is the annual 3.3 million home loans the Federal Reserve bought to save our real estate market from ruin. And if you read the papers, real estate sales are picking up --gee, I wonder why? --and for how long?
Tuesday, April 23, 2013
Surfing The Kondratieff Wave, Reprinted from 2006
Here is a reprint of my second post as a blogger way back in May of 2006 and reprinted again in March 2009. Click on the link in this article, you won't be disappointed.
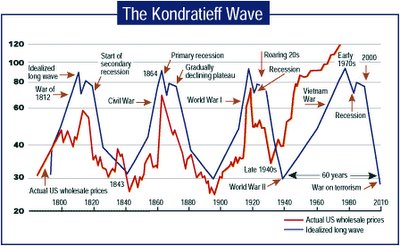 If you're into investment cycles and charts, the Kondratieff Wave is one to examine. Basically the boom and bust cycle had a 60 year span. Here is a link to more detail http://www.kwaves.com/kond_overview.htm Credit the picture above from this link.
The cycle this time around is a little long in the tooth. There is a reason for this and I believe as do some others, that it has to do with the increase in the length of the average persons life span.It use to be about 60 years now we are up to about 75 years.
Each generation has a group of elders that can draw from past mistakes. We are at a point right now, that the follies of the 1920's and 1930's are not part of our "group memory" any more. Most people from that era would be at least 100 years old now. Now when you quote some historical aspect a cause of the last depression, you hear the phrase,"Its different this time."
People today think that the interest only no money down mortgage is something new. Well it isn't. They were written right up to the collapse in 1929. The banks soon realized that it was like the neighbor taking out your daughter for a "test drive" before he married her. The responsibility factor was missing.
Cycles are usually displayed as circles that would follow through phases and complete back where they started. I think that this is not a true analogy of what is happening here. If you start with a spiral going out from the center, this more correctly displays "history repeating itself." It s not quite the same, things have changed somewhat.
People are consuming more and more, and with that, comes the creation of more debt. It is this debt that will be marked to market. Mr. Kondratieff's theory suggests that all of this debt will disappear and the money supply will contract accordingly (drastically in this case).
I don't think that people fully realize how money disappears. Take Lucent Technologies a few years back. It sold for $80 per share and went down to $2. Somebody owned it the whole way down.
What really scares me today, is the people with savings and retirement funds, they have been funding this whole thing. The market will always go up (believe that and I'll tell you another). The trouble is, a majority of the owners of wealth, are going to want to get out of the market pretty soon and they are at the head of the line-- the baby boomer's.The baby boomer's think that this will be a relaxing walk into retirement. More likely its going to be one hell of a panic. If Mr Kondratieff is right, there will be a drastic contraction of the money supply because of the debt marked to market, and because of this, commodities should fall in price.
My question is this. If the world population has increased 4 times in the last 60 years and most of these governments have been printing money at a very vigorous rate, can gold and silver still be considered commodities? I think that they reside outside the realm of consumables.
As an addition to the original post, here is a little bit of video from You-Tube that everyone is carrying.
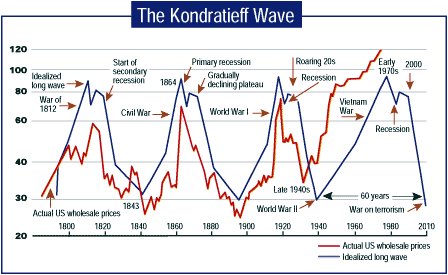 If you're into investment cycles and charts, the Kondratieff Wave is one to examine. Basically the boom and bust cycle had a 60 year span. Here is a link to more detail http://www.kwaves.com/kond_overview.htm Credit the picture above from this link.
The cycle this time around is a little long in the tooth. There is a reason for this and I believe as do some others, that it has to do with the increase in the length of the average persons life span.It use to be about 60 years now we are up to about 75 years.
Each generation has a group of elders that can draw from past mistakes. We are at a point right now, that the follies of the 1920's and 1930's are not part of our "group memory" any more. Most people from that era would be at least 100 years old now. Now when you quote some historical aspect a cause of the last depression, you hear the phrase,"Its different this time."
People today think that the interest only no money down mortgage is something new. Well it isn't. They were written right up to the collapse in 1929. The banks soon realized that it was like the neighbor taking out your daughter for a "test drive" before he married her. The responsibility factor was missing.
Cycles are usually displayed as circles that would follow through phases and complete back where they started. I think that this is not a true analogy of what is happening here. If you start with a spiral going out from the center, this more correctly displays "history repeating itself." It s not quite the same, things have changed somewhat.
People are consuming more and more, and with that, comes the creation of more debt. It is this debt that will be marked to market. Mr. Kondratieff's theory suggests that all of this debt will disappear and the money supply will contract accordingly (drastically in this case).
I don't think that people fully realize how money disappears. Take Lucent Technologies a few years back. It sold for $80 per share and went down to $2. Somebody owned it the whole way down.
What really scares me today, is the people with savings and retirement funds, they have been funding this whole thing. The market will always go up (believe that and I'll tell you another). The trouble is, a majority of the owners of wealth, are going to want to get out of the market pretty soon and they are at the head of the line-- the baby boomer's.The baby boomer's think that this will be a relaxing walk into retirement. More likely its going to be one hell of a panic. If Mr Kondratieff is right, there will be a drastic contraction of the money supply because of the debt marked to market, and because of this, commodities should fall in price.
My question is this. If the world population has increased 4 times in the last 60 years and most of these governments have been printing money at a very vigorous rate, can gold and silver still be considered commodities? I think that they reside outside the realm of consumables.
As an addition to the original post, here is a little bit of video from You-Tube that everyone is carrying.
Tuesday, April 16, 2013
A Precious Metals Market Perspective
There are three ways to own precious metals, take physical possession of the metal, or let a proxy hold the gold for you in a storage vault, or trade the metal with your broker using ETF’s (Exchange Traded Funds).
In the first process, taking physical possession, you have the metal to hold in your greedy little hands. In the second process someone else holds your gold in their greedy hands and there is a good possibility if every depositor wanted delivery, it just wouldn’t happen. And in the third method of “owing” the metal is through ETF trading. This last method is kind of paper trading of the metal. A person can buy and sell and never really deal with the physical metal.
There is one problem though. Physical gold, silver and platinum are real. A lot of these markets are hypothetical. They trade on the price of the commodity, with the buyer and seller not the least bit interested in taking possession of the precious metal. A buyer sells 1000 ounces of gold for September delivery and buys them back before the due date to avoid having to make delivery.
I’ve made several trips to a gold and bullion wholesaler. I was converting my junk silver and gold. People are buying, not selling. And I must admit when I first went there, I thought I was telling the owner something new about Obama printing dollars and how I wanted to preserve my buying power. The last time I was there, an elderly couple was telling him the same thing. And Chuck patiently listened to them.
So there are really two markets, one that deals in physical delivery of the metal to the buyer and one that deals with the change in price for the holder of the contract.
The precious metals have dropped in price considerably in the last two days. The thing to look at is the physical delivery. People on the street think that now is a good time to buy gold, since the price is down about $400 from its highs.
It appears the ETF’s and futures markets are where the battle over price of precious metals is being fought. A lot of those contracts can be bought with only 6% down. So Monday there had to have been some pretty heavy margin calls and if you didn’t make the margin call, you got sold out.
On a local level, I only have my own observations to report, but some bullion dealers around here are running short of gold and platinum maple leafs. It now takes a couple of days to fill an order. And it’s been that way since January. What we are looking at is not a real shortage, but it suggests more people are buying than those selling physical precious metals. Remember there is a $48 dollar premium on the purchase of gold and platinum per ounce; so you’re not going to change your mind on a whim.
I think that Joe Sixpack has figured it out. The banks pay zip for interest. Costs are going up and paychecks are going down. Silver rounds can be purchased for about a buck above spot. Physical ownership has a real feeling to it; you’re in control. It’s rather strange to see someone come in to this precious metal wholesalers shop with a stack of 100 20 dollar bills and leave with 60 ounces of silver. That buyer just made a statement; the banking system sucks. GOT SILVER?
Monday, April 08, 2013
The Governments Good Intentions
Our government thinks that the American dream is home ownership, a college education for everyone. and of course, health care taxes for everyone (under the age of 65).
We just went through a housing bubble crash. Notice the people that sold their homes got cash and the people who bought them got a house they couldn’t afford. So if you paid nothing down and moved in, the term “Underwater” kind of evokes sympathy from the reader, but in most cases it didn’t cost much to move in. In fact, to rent out here, you need first and last month’s rent which is about $3,500. So for as little as $1,500 you can still buy a home out here.
I was listening to Gov. Huckabee on FOX yesterday and he question the current government policy of lowering credit requirements for new home buyers; “Weren’t low down payments the cause of the housing bubble?” Well, kind of, but the government is in a situation where selling these foreclosures to someone new, improves their balance sheet somewhat (since they already own them). The worse that can happen is that they get the house back. The real problem is the financing.
Before the crash, the banks packaged and sold this “toxic waste” (that’s what the banks called the stuff) to investors. Now that won’t happen in today’s market for two reasons, everyone knows the stuff is bad already, and you could get some jail time for selling it. Now you see why Bernanke is buying real estate paper. Once the Fed purchases the paper, Fannie and Freddie have more money to offer for home loans. Taking advantage of the American dream of home ownership, the government transfers these foreclosures to our unsuspecting kids. The average home buyer is not interested in the cost, only the monthly payments. The higher the price, the more the homeowner pays in property taxes. “Oh Goodie” says Uncle Sam.
Here is where it gets interesting. Student loans offer a method to increase the amount of debt owed by our kids. Remember the dreams we had of future success after completing college? It’s a little like buying 100K in lottery tickets. You’ll read about the winners. I’ve known people who’ve had 30K in Visa debts and that is about where the debt goes from being manageable to unmanageable. At that point they file for bankruptcy. And of course with the student loans, bankruptcy is not an option.
.
During tough times, the amount owed on a student loan could double in just 12 years. This is where home ownership and a wife that wants to stick around, are all part of a meaningless dream world that will fall apart. Too many debts will kill any marriage ever made. There is a way to escape this trap that Congress overlooked. Move to another country like Australia (sshhh that’s a secret).
Then on top of that I was doing my taxes and looking at what I, the wife and son pay for health care coverage combining our payments with our employers—about 20K. And this is just basic coverage. Obama care hasn’t even really kicked in yet. Why do I get the feeling that we will be paying a lot more real soon?
Let’s get rid of Fannie and Freddie. We don’t need to save homeowners who have no skin in the game. Give our kids a shot at a home that has a reasonable price tag. Modify student loans so bankruptcy is an option. Teach the lenders not to fiddle with kids right out of high school. It’s literally a license to steal from those too inexperienced to know what they are signing. As for Obama care, this law eliminates the decision many families made about what they considered necessary, like auto or health insurance. Why worry about your right to bear arms when the government can tell you what you are going to buy with your paycheck?
Do you get the feeling that all of this government help we’re getting is making things a lot worse?
We have a government that has successfully screwed up the housing market by trashing the bond market interest rates. The student loan program works for all the wrong reasons. It reminds me of those “fog a mirror“ real estate loans. The good thing, when your two years of unemployment runs out, your student loan will put food on the table for four more years--Then apply for your passport (wink wink).
Look for the work week to be shortened to 32 hours (to get more people covered by Obamacare). And of course Congress will have to raise the minimum wage by $4 per hour so workers don’t starve to death making their mandatory health care payment. On top of that, the government will probably lay off all of the people responsible for managing these programs to teach us a lesson for wanting leaner government (it gets meaner as it gets leaner). All of this lends more credence to the saying, “The road to hell is paved with good intentions.” This isn't the hike we signed up for. "We are not out of the woods yet" and Obama can't smell the smoke.
We just went through a housing bubble crash. Notice the people that sold their homes got cash and the people who bought them got a house they couldn’t afford. So if you paid nothing down and moved in, the term “Underwater” kind of evokes sympathy from the reader, but in most cases it didn’t cost much to move in. In fact, to rent out here, you need first and last month’s rent which is about $3,500. So for as little as $1,500 you can still buy a home out here.
I was listening to Gov. Huckabee on FOX yesterday and he question the current government policy of lowering credit requirements for new home buyers; “Weren’t low down payments the cause of the housing bubble?” Well, kind of, but the government is in a situation where selling these foreclosures to someone new, improves their balance sheet somewhat (since they already own them). The worse that can happen is that they get the house back. The real problem is the financing.
Before the crash, the banks packaged and sold this “toxic waste” (that’s what the banks called the stuff) to investors. Now that won’t happen in today’s market for two reasons, everyone knows the stuff is bad already, and you could get some jail time for selling it. Now you see why Bernanke is buying real estate paper. Once the Fed purchases the paper, Fannie and Freddie have more money to offer for home loans. Taking advantage of the American dream of home ownership, the government transfers these foreclosures to our unsuspecting kids. The average home buyer is not interested in the cost, only the monthly payments. The higher the price, the more the homeowner pays in property taxes. “Oh Goodie” says Uncle Sam.
Here is where it gets interesting. Student loans offer a method to increase the amount of debt owed by our kids. Remember the dreams we had of future success after completing college? It’s a little like buying 100K in lottery tickets. You’ll read about the winners. I’ve known people who’ve had 30K in Visa debts and that is about where the debt goes from being manageable to unmanageable. At that point they file for bankruptcy. And of course with the student loans, bankruptcy is not an option.
.
During tough times, the amount owed on a student loan could double in just 12 years. This is where home ownership and a wife that wants to stick around, are all part of a meaningless dream world that will fall apart. Too many debts will kill any marriage ever made. There is a way to escape this trap that Congress overlooked. Move to another country like Australia (sshhh that’s a secret).
Then on top of that I was doing my taxes and looking at what I, the wife and son pay for health care coverage combining our payments with our employers—about 20K. And this is just basic coverage. Obama care hasn’t even really kicked in yet. Why do I get the feeling that we will be paying a lot more real soon?
Let’s get rid of Fannie and Freddie. We don’t need to save homeowners who have no skin in the game. Give our kids a shot at a home that has a reasonable price tag. Modify student loans so bankruptcy is an option. Teach the lenders not to fiddle with kids right out of high school. It’s literally a license to steal from those too inexperienced to know what they are signing. As for Obama care, this law eliminates the decision many families made about what they considered necessary, like auto or health insurance. Why worry about your right to bear arms when the government can tell you what you are going to buy with your paycheck?
Do you get the feeling that all of this government help we’re getting is making things a lot worse?
We have a government that has successfully screwed up the housing market by trashing the bond market interest rates. The student loan program works for all the wrong reasons. It reminds me of those “fog a mirror“ real estate loans. The good thing, when your two years of unemployment runs out, your student loan will put food on the table for four more years--Then apply for your passport (wink wink).
Look for the work week to be shortened to 32 hours (to get more people covered by Obamacare). And of course Congress will have to raise the minimum wage by $4 per hour so workers don’t starve to death making their mandatory health care payment. On top of that, the government will probably lay off all of the people responsible for managing these programs to teach us a lesson for wanting leaner government (it gets meaner as it gets leaner). All of this lends more credence to the saying, “The road to hell is paved with good intentions.” This isn't the hike we signed up for. "We are not out of the woods yet" and Obama can't smell the smoke.
Subscribe to:
Posts (Atom)